Filing a renters insurance claim in the USA can feel complicated when you are already dealing with stolen belongings, fire damage, water damage, or a rental home that is temporarily unlivable. The process becomes much easier when you understand what your policy covers, document the loss carefully, and communicate with the insurance company in an organized way.
A useful way to approach a renters insurance claim is to think of it as an evidence packet rather than simply a report of what happened. Your insurer needs to understand when the loss occurred, what caused it, which belongings were affected, what those items were worth, and what expenses you incurred because of the event. Photos, videos, receipts, serial numbers, bank records, police reports when appropriate, and written communication can all help create that clear record.
Renters insurance rules and claim-handling requirements can differ between states and policies, so your own insurance contract remains the most important document. The following process provides a practical framework that renters across the United States can use when preparing and managing a claim.
Understand What Your Renters Insurance Policy Covers
Before estimating how much an insurer may pay, review your declarations page, coverage limits, deductible, exclusions, and personal property settlement terms. Renters insurance commonly includes personal property coverage, personal liability protection, and loss-of-use or additional living expense coverage. Your landlord’s insurance normally protects the building rather than the belongings you personally own.
Pay particular attention to whether your belongings are insured for replacement cost or actual cash value. Replacement cost coverage generally considers the cost of replacing an insured item with a comparable new item, subject to policy terms and limits. Actual cash value typically considers depreciation, which can reduce the payment for older belongings.
Make Sure the Cause of Loss Is Covered
Coverage depends heavily on what caused the damage. Theft, fire, smoke, and certain types of sudden water damage may be covered when they meet the terms of the policy. However, exclusions matter. For example, standard renters insurance generally does not cover flooding caused by water accumulating and entering from outside. Renters who need that protection can obtain separate contents coverage through programs such as the National Flood Insurance Program where available.
Do not assume that every event involving water is treated the same way. Damage from a suddenly broken pipe inside a rental can be handled differently from damage caused by rising floodwater. Ask the insurer which policy provision applies if the cause is unclear.
Report the Loss as Soon as Possible
Contact your insurer or insurance agent promptly after discovering a covered loss. Many policies require policyholders to provide timely notice. Claims can commonly be started by telephone, website, mobile application, or through an agent.
🔥 Don’t Miss These Opportunities
Have your policy number, rental address, date of loss, contact information, and a short factual description ready. Ask for your claim number and the contact details of the person handling the claim. Save this information because you will probably use it throughout the process.
Protect Yourself and Prevent Additional Damage
Personal safety comes first. Do not enter an unsafe apartment or attempt repairs that could expose you to fire, electrical hazards, contaminated water, structural damage, or other dangerous conditions.
When it can be done safely, take reasonable steps to prevent additional damage. For example, you might move unaffected belongings away from leaking water or arrange safe temporary protection for exposed property. Keep receipts for reasonable emergency expenses and avoid making major permanent changes before the insurer has had an opportunity to inspect the loss when an inspection is necessary.
Photograph and Document Everything Before Cleanup
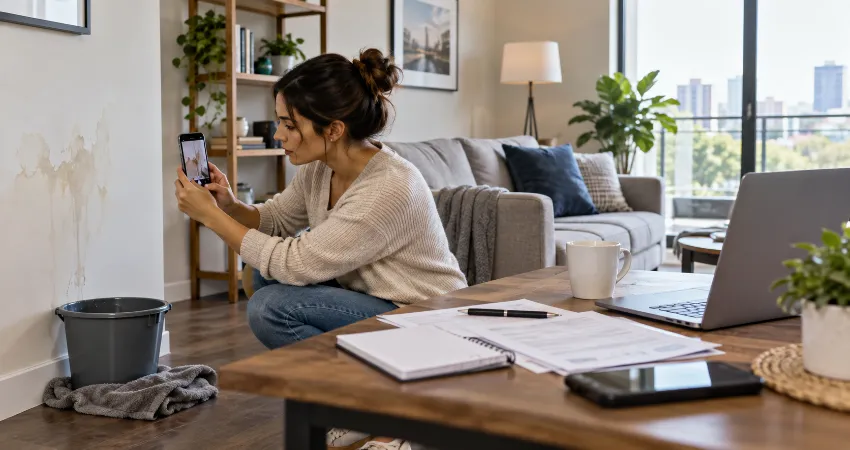
One of the most valuable steps in a renters insurance claim is creating a visual record before damaged property is removed. Take wide photographs of each affected room, then take closer pictures of individual damaged items. Video can help show the overall extent of the loss.
Do not immediately discard damaged belongings unless they create a health or safety problem or the insurer authorizes disposal. An adjuster may need photographs, descriptions, or physical inspection of certain items.
Create a Detailed Personal Property Loss List
Build an itemized list rather than submitting a vague estimate such as “electronics damaged.” For each item, record the item type, brand, model, approximate purchase date, original purchase price, and estimated replacement cost when possible.
Receipts are helpful, but they are not the only records that may help establish ownership. Photographs taken before the loss, online purchase histories, credit card statements, bank records, warranty records, product registrations, emails, and photographs showing the item inside your home can provide useful supporting information.
If many belongings were destroyed, reconstruct your inventory room by room. Mentally walk through the apartment and consider furniture, clothing, electronics, cookware, bedding, tools, books, household supplies, hobby equipment, and other everyday possessions that are easy to overlook.
Keep Records of Temporary Living Expenses
If a covered loss makes your rental home uninhabitable, the loss-of-use or additional living expense section of your policy may help with certain increased living costs. Depending on the policy, eligible expenses may include temporary lodging and other necessary additional costs caused by displacement.
Keep every relevant receipt and separate your normal expenses from additional expenses created by the loss. Coverage does not necessarily mean every expense will be reimbursed, and limits or time restrictions may apply.
Work Carefully With the Claims Adjuster
An insurance adjuster may contact you to review the circumstances, examine documentation, inspect damage, or request a formal proof-of-loss statement. Answer questions accurately and avoid guessing when you do not know an answer.
Keep a simple claim journal containing the date of each call, the name of the person you spoke with, documents requested, documents submitted, and any important commitments or deadlines. This small habit can prevent confusion when a claim lasts several weeks or involves multiple representatives.
Review the Settlement Instead of Looking Only at the Total
When the insurer provides an estimate or settlement explanation, examine how the amount was calculated. Check your deductible, coverage limits, depreciation, special limits for certain categories of property, and any items that were excluded.
For replacement cost policies, some insurers may initially account for depreciation and provide additional payment after eligible property has actually been replaced and documentation is submitted. The exact process depends on the policy, so ask the adjuster to explain how recoverable depreciation or replacement documentation works in your claim.
What to Do If You Disagree With the Claim Decision?
A disagreement does not automatically mean the process is finished. First, ask the insurer for a written explanation identifying the policy language used to calculate, limit, or deny the claim. Compare that explanation with your policy and supporting documentation.
If information was missing, submit it and ask for reconsideration. You can also ask to speak with a claims supervisor. If you believe the insurer has improperly delayed, denied, or handled the claim and you cannot resolve the issue directly, your state’s Department of Insurance may provide consumer assistance or accept a formal complaint. Insurance regulation in the United States is primarily state based, so procedures and legal timelines vary by jurisdiction.
A Simple Renters Insurance Claim Checklist
A practical claim workflow is: confirm that everyone is safe, notify the landlord when necessary, report theft or another reportable event to the appropriate authority, contact your insurer promptly, photograph the loss, protect property from additional damage, prepare an itemized inventory, collect proof of ownership, save receipts, respond to reasonable insurer requests, and keep copies of everything you submit. Before accepting the final settlement, compare the payment explanation with your policy limits and settlement terms.
FAQs About Renters Insurance Claims
1. How soon should I file a renters insurance claim?
You should generally notify your insurer as soon as reasonably possible after discovering the loss. Policies commonly contain duties requiring timely notice. Prompt reporting also makes it easier to preserve photographs, receipts, witness information, and other evidence. Check your policy because specific requirements can differ.
2. Do I need receipts for everything I claim?
Receipts can strengthen a claim, but losing a receipt does not necessarily mean you cannot document ownership. Depending on the insurer and circumstances, purchase emails, card statements, photographs, product registrations, warranty documents, online order histories, and other records may help establish that you owned an item.
3. Does my landlord’s insurance cover my belongings?
Generally, no. A landlord’s property policy primarily protects the building and the landlord’s insured property or interests. Your furniture, clothing, computers, televisions, and other personal belongings normally require your own renters insurance or another applicable policy.
4. Will renters insurance pay for a hotel?
It may when a covered loss makes the insured rental uninhabitable and your policy includes loss-of-use or additional living expense coverage. Limits and conditions apply. Contact the insurer early, ask what expenses qualify, and keep detailed receipts for temporary housing and other eligible additional costs.
5. What happens if my belongings are stolen?
Theft is commonly covered under renters insurance, subject to the policy’s terms, deductible, exclusions, and limits. Report the theft to law enforcement when appropriate and obtain the report information. Provide your insurer with an itemized list and as much evidence of ownership and value as possible.
6. Does renters insurance cover flood damage?
Standard renters insurance generally does not cover damage caused by flooding from rising or accumulating outside water. Separate flood insurance can provide contents protection for renters. However, some types of sudden internal water damage may be handled differently, so the specific cause of the water damage is important.
7. What is the difference between replacement cost and actual cash value?
Replacement cost coverage generally uses the cost of replacing covered belongings with comparable new property, subject to policy requirements and limits. Actual cash value generally accounts for depreciation caused by age and use. That difference can significantly affect the amount paid for older furniture, electronics, appliances, and other belongings.
8. Should I throw away damaged property immediately?
Usually, it is better to document damaged belongings and ask the insurer before disposing of them unless keeping them would create a safety or health problem. Take detailed photographs and videos first. An adjuster may need information about the item’s condition before the insurer completes its evaluation.
9. Can an insurance company deny a renters insurance claim?
Yes. A claim may be denied when the cause of loss is excluded, the policy was not active, the property was not covered, limits have been reached, or other policy conditions apply. If a claim is denied, request the decision in writing and ask which policy provision supports the decision.
10. Where can I get help if I believe my insurer handled the claim unfairly?
Start by requesting a clear explanation from the insurer and asking a supervisor to review unresolved issues. Keep copies of the policy, claim correspondence, photographs, estimates, receipts, and your communication log. If the dispute remains unresolved, contact your state’s insurance department. State regulators can provide consumer information and may investigate complaints involving issues such as improper delays, denials, or failures to follow applicable insurance requirements.
Conclusion
Filing a renters insurance claim in the USA becomes much more manageable when you focus on documentation, organization, and timely communication. Understand your coverage, photograph the damage, create a detailed inventory, save receipts, keep a communication log, and carefully review the insurer’s settlement explanation.
Most importantly, treat your claim as a documented timeline supported by evidence. That approach gives both you and the insurer a clearer picture of the loss and can make the entire claim process easier to navigate.