Renters insurance requirements for US rental properties can be confusing because there is no single nationwide rule that applies to every apartment, house, landlord, and tenant. In many rental situations, the real requirement comes from the lease agreement rather than a general federal mandate. State laws can also control whether a landlord may require coverage, how much liability protection may be requested, and what notices or exceptions must be provided.
For renters, this distinction matters before signing a lease. A property owner may carry insurance on the building, but that policy is primarily designed to protect the owner’s property and financial interests. It normally does not replace a renter’s furniture, electronics, clothing, or other personal belongings after a covered loss. Renters insurance is designed to fill important parts of that gap.
The practical approach is therefore simple: read the insurance clause in the lease, identify the required coverage, check the law where the property is located, and compare that requirement with the actual policy being purchased. A policy should protect the renter, not merely satisfy a paperwork requirement.
Is Renters Insurance Legally Required in the United States?
There is no general federal law requiring every residential tenant in the United States to purchase renters insurance. However, landlords may be able to make insurance a condition of tenancy through a rental agreement, subject to applicable state and local laws. This means a tenant can encounter a valid insurance requirement even when the government does not independently require every renter to carry a policy.
Requirements can vary substantially between jurisdictions. Some states specifically regulate landlord-required liability coverage, notices, documentation, or exceptions. Consequently, a lease clause that is acceptable in one state should not automatically be assumed to work the same way in another.
Why Landlords Require Renters Insurance?
Landlords commonly focus on renters insurance because tenant-caused incidents can create expensive disputes. Imagine that a renter accidentally causes a kitchen fire or overflowing water damages another unit. Depending on the facts and policy terms, liability coverage may help address qualifying claims involving damage for which the tenant is legally responsible.
From a property-management perspective, the key value is risk separation. The landlord maintains coverage appropriate for the building, while the tenant maintains coverage for personal possessions and personal liability. This does not eliminate disputes or guarantee that every loss will be covered, but it creates a clearer insurance structure when an unexpected event occurs.
What Coverage May a Landlord Require?
A lease will often concentrate on personal liability insurance. A landlord may state a minimum liability limit and require the renter to maintain that coverage throughout the tenancy. The appropriate amount depends on the lease, state law, insurer, property, and individual circumstances.
🔥 Don’t Miss These Opportunities
A normal renters policy may provide more than liability protection. It can include personal property coverage for qualifying losses involving the renter’s belongings, additional living expenses when a covered event makes the home temporarily uninhabitable, and certain medical payments or liability benefits. Policy limits, deductibles, exclusions, and covered causes of loss should always be reviewed rather than assuming that all policies offer identical protection.
State Laws Can Change the Requirements
State-specific rules are one of the most important parts of renters insurance compliance. Oregon provides a useful example. Its residential landlord and tenant law allows certain landlords to require renter’s liability insurance in a written rental agreement but regulates the amount, notice process, documentation, landlord insurance obligations, and certain exceptions. Oregon law also provides protections for qualifying lower-income households and certain publicly subsidized units.
Virginia takes another detailed approach. State law allows a landlord to require renters insurance when specified in the rental agreement. A tenant who chooses a separate qualifying policy may provide written proof of coverage, while the statute also addresses situations in which coverage obtained through the landlord is used. These examples demonstrate why generic national advice should never replace checking the law applicable to the property’s location.
Proof of Renters Insurance
When coverage is required, tenants are often asked to provide evidence before moving in or shortly afterward. The document may identify the insured person, policy period, insurer, property address, and applicable coverage. Property managers may also request updated documentation when a policy renews.
Tenants should confirm exactly what the lease requests. Being listed as an interested party for notification purposes is not necessarily the same as being named as an additional insured. These terms can have different legal and insurance consequences. A renter should avoid changing policy designations simply because the terminology sounds similar.
What Happens if Required Coverage Expires?
If renters insurance is an enforceable lease requirement, allowing the policy to lapse may create a lease-compliance problem. The consequences depend on the rental agreement and applicable law. Some property-management programs may notify the tenant, request updated proof, or apply a landlord-arranged insurance process where legally permitted.
The safest approach is to prevent a coverage gap. Tenants can keep renewal notices, confirm automatic payment details, and provide updated evidence when requested. Landlords should likewise apply written requirements consistently and follow required notice procedures rather than relying on informal rules.
Landlord Insurance Does Not Replace Renters Insurance
One of the most common misunderstandings is assuming that the owner’s property insurance protects everything inside the rental unit. A landlord’s policy and a tenant’s renters policy serve different purposes. The building owner’s insurance may protect the structure and the owner’s interests, while the renter may need separate coverage for personal belongings and personal liability.
For example, if an insured event damages both an apartment building and a renter’s belongings, the building and the tenant’s personal property may involve different policies and claims. Renters should therefore evaluate the value of their possessions instead of assuming the landlord will reimburse them.
How Tenants Should Evaluate a Lease Insurance Clause?
Before signing, locate every section referring to insurance, liability, damage, indemnification, or proof of coverage. Write down the required liability limit, deadline, approved documentation, and any instructions concerning interested-party status. Then compare those provisions with quotes from licensed insurers.
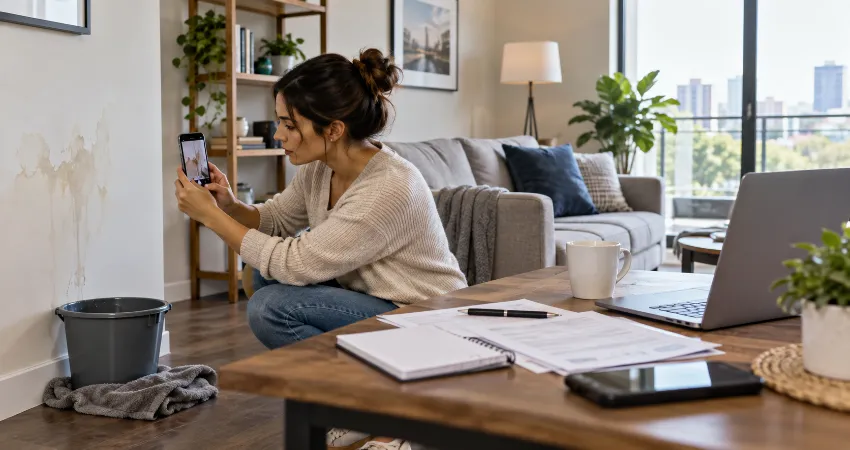
It is also useful to create a basic home inventory. Photograph important belongings, record major purchases, and estimate replacement costs. This helps the renter choose a realistic personal-property limit and can provide useful documentation after a covered loss.
Important Coverage Gaps to Consider
Renters insurance should not be viewed as protection against every possible event. Coverage is controlled by the actual policy. Certain hazards may be excluded or require separate coverage. Flood damage is a particularly important example because standard residential policies may not provide the protection a renter expects. Earthquake coverage can also require separate consideration depending on the policy and location.
High-value jewelry, collectibles, electronics, business property, or other specialized belongings may also be subject to limits. Reading exclusions and sublimits is often more valuable than choosing a policy solely by its price.
Renters Insurance Checklist Before Moving In
A practical compliance check should answer six questions: Does the lease require insurance? What liability limit is specified? When must coverage begin? What proof must be submitted? Does state or local law restrict the requirement? Does the selected policy actually provide adequate personal protection? Keeping the lease, policy declaration documents, inventory records, and renewal information together makes future verification much easier.
FAQs About Renters Insurance Requirements
1. Is renters insurance mandatory for every US renter?
No. There is no universal rule making renters insurance compulsory for every residential tenant nationwide. However, a landlord may be permitted to require it through the lease. State and local law should be checked because restrictions and exceptions can differ.
2. Can a landlord require renters insurance before move-in?
In many jurisdictions, a landlord can make qualifying coverage a condition of tenancy. The lease or application documents may require proof before possession of the unit. State law can regulate how that requirement is disclosed or applied.
3. How much renters insurance does a tenant need?
There is no single amount suitable for everyone. A lease may establish a liability minimum, while personal-property coverage should reflect the approximate cost of replacing the renter’s possessions. Policy limits should be evaluated together with deductibles and exclusions.
4. Does renters insurance protect the apartment building?
Renters insurance is primarily intended to protect the renter’s interests. Liability coverage may respond to certain covered situations in which the renter is legally responsible for damage, but the building owner normally maintains separate property insurance for the structure.
5. Does the landlord’s insurance cover a tenant’s belongings?
Generally, a property owner’s building insurance should not be relied upon to replace a tenant’s personal possessions. Tenants commonly need their own renters policy for qualifying losses involving furniture, clothing, electronics, and other covered belongings.
6. Can a landlord require proof every year?
A lease or applicable law may allow reasonable verification that required coverage remains active. Tenants should retain renewal documents and provide acceptable proof when properly requested. Specific documentation rules can vary by jurisdiction.
7. What happens if renters insurance is canceled?
If continuous insurance is required under an enforceable lease provision, cancellation can create a compliance issue. The landlord’s available response depends on state law and the rental agreement, so the tenant should restore qualifying coverage promptly and provide updated documentation.
8. Do roommates automatically share renters insurance?
Not necessarily. Coverage depends on the policy language and the relationships between household members. A roommate who is not considered an insured under the policy may need separate coverage. Each adult should confirm their status with the insurer rather than assuming protection exists.
9. Does standard renters insurance cover floods?
Standard renters policies should not automatically be assumed to cover flood losses. Renters living in flood-prone areas should review their policy carefully and investigate separate flood coverage when appropriate. Similar attention should be given to other excluded hazards.
10. What should a renter check before buying a policy?
Start with the lease requirement, then compare personal-property limits, liability coverage, loss-of-use protection, deductibles, exclusions, and any special limits for valuable items. Confirm that the policy satisfies the lease while also providing meaningful protection for the renter’s actual financial risks.
Conclusion
Renters insurance requirements for US rental properties are determined largely by lease terms and state or local law rather than one nationwide mandate. A well-chosen policy can protect personal belongings, provide liability protection, and help with qualifying temporary living expenses.
Before signing a lease, tenants should verify the exact requirement, understand their policy, document their possessions, and check the rules that apply in the state where the property is located.